Between November 2025 and February 2026 we held discovery interviews, mostly with people who run localization at technology, e-commerce and consumer companies. This is what they told us about AI in practice, the pace of change, what they need from a language partner, and how they measure their work.
Read the five findings ↓Updated 23 October 2026. See the update note.
Drawn from discovery interviews held between November 2025 and February 2026. Most interviewees run localization in-house at technology, e-commerce and consumer companies; a few work on the vendor or consulting side. These are qualitative findings about the people we spoke to, not a representative survey of the profession.
Two teams have renamed the function so that its name no longer refers to translation or localization, and several sit in Product or Growth rather than Marketing. Two interviewees linked these choices to more visibility and an earlier say in decisions.
Among the in-house teams we spoke to, AI was mostly used for specific content types or still at pilot stage. Those using AI in production kept humans in the loop, at least for content published in their own brand's voice.
One leader described the past period as exhausting, with new tools and proofs of concept that never reach a stable operating phase. Several described internal expectations of AI that do not match what their teams can deliver.
Recurring themes: help with solving problems, consistent linguists who know the brand, and adapting to the client's tools and processes. One interviewee also singled out accountability.
Several of the leaders we spoke to found it difficult to attribute business outcomes to localization. Some are moving towards measures their stakeholders recognise, and towards tiering content by risk.
Several of the teams we spoke to are working to be seen as more than a service desk that processes translation requests.
Two teams have renamed the function so that its name no longer refers to translation or localization. The change is deliberate: it presents localization as shaping how a company shows up in each market.
Where localization reports varies. Among the people we interviewed, teams sat in Product, in Growth or Marketing, and in one case reported directly to the CEO. Two interviewees linked their placement to more visibility and an earlier say in decisions.
Team sizes varied widely, from one person covering several European markets alone to larger teams with dedicated linguists for their main markets.
AI came up in every conversation, but not in the way the headlines suggest.
The range was wide, from teams that had not yet integrated AI into their localization workflows to teams using it in production.
Most of the in-house teams we spoke to used AI for specific content types, or had pilots that had shown promise for one use case but had not yet scaled.
Several interviewees found that AI does better with well-resourced languages than with low-resource ones, and two found that it does better with longer, well-structured content than with short strings written without context.
Most of the AI uses that worked were narrow and specific. None of the success stories we heard were about plugging in AI and scaling it to everything.
Several described pressure from the business to use AI as widely as possible without a defined strategy. One described a pace of change faster than the team could absorb.
We did not expect this theme.
One leader described the past period as exhausting, and another described the strain on the wider industry in stark terms. The cause they described is structural rather than ordinary work stress: a long run of change without a stable operating phase. One interviewee described the team as never reaching that operational phase: constantly building proofs of concept, testing tools and redesigning workflows instead of settling into a steady state where it can optimize and execute.
Internal expectations add to the pressure. One interviewee's sales colleagues expected new languages to be added almost instantly with AI. The gap between what other departments imagine AI can do and what localization teams can actually deliver creates friction.
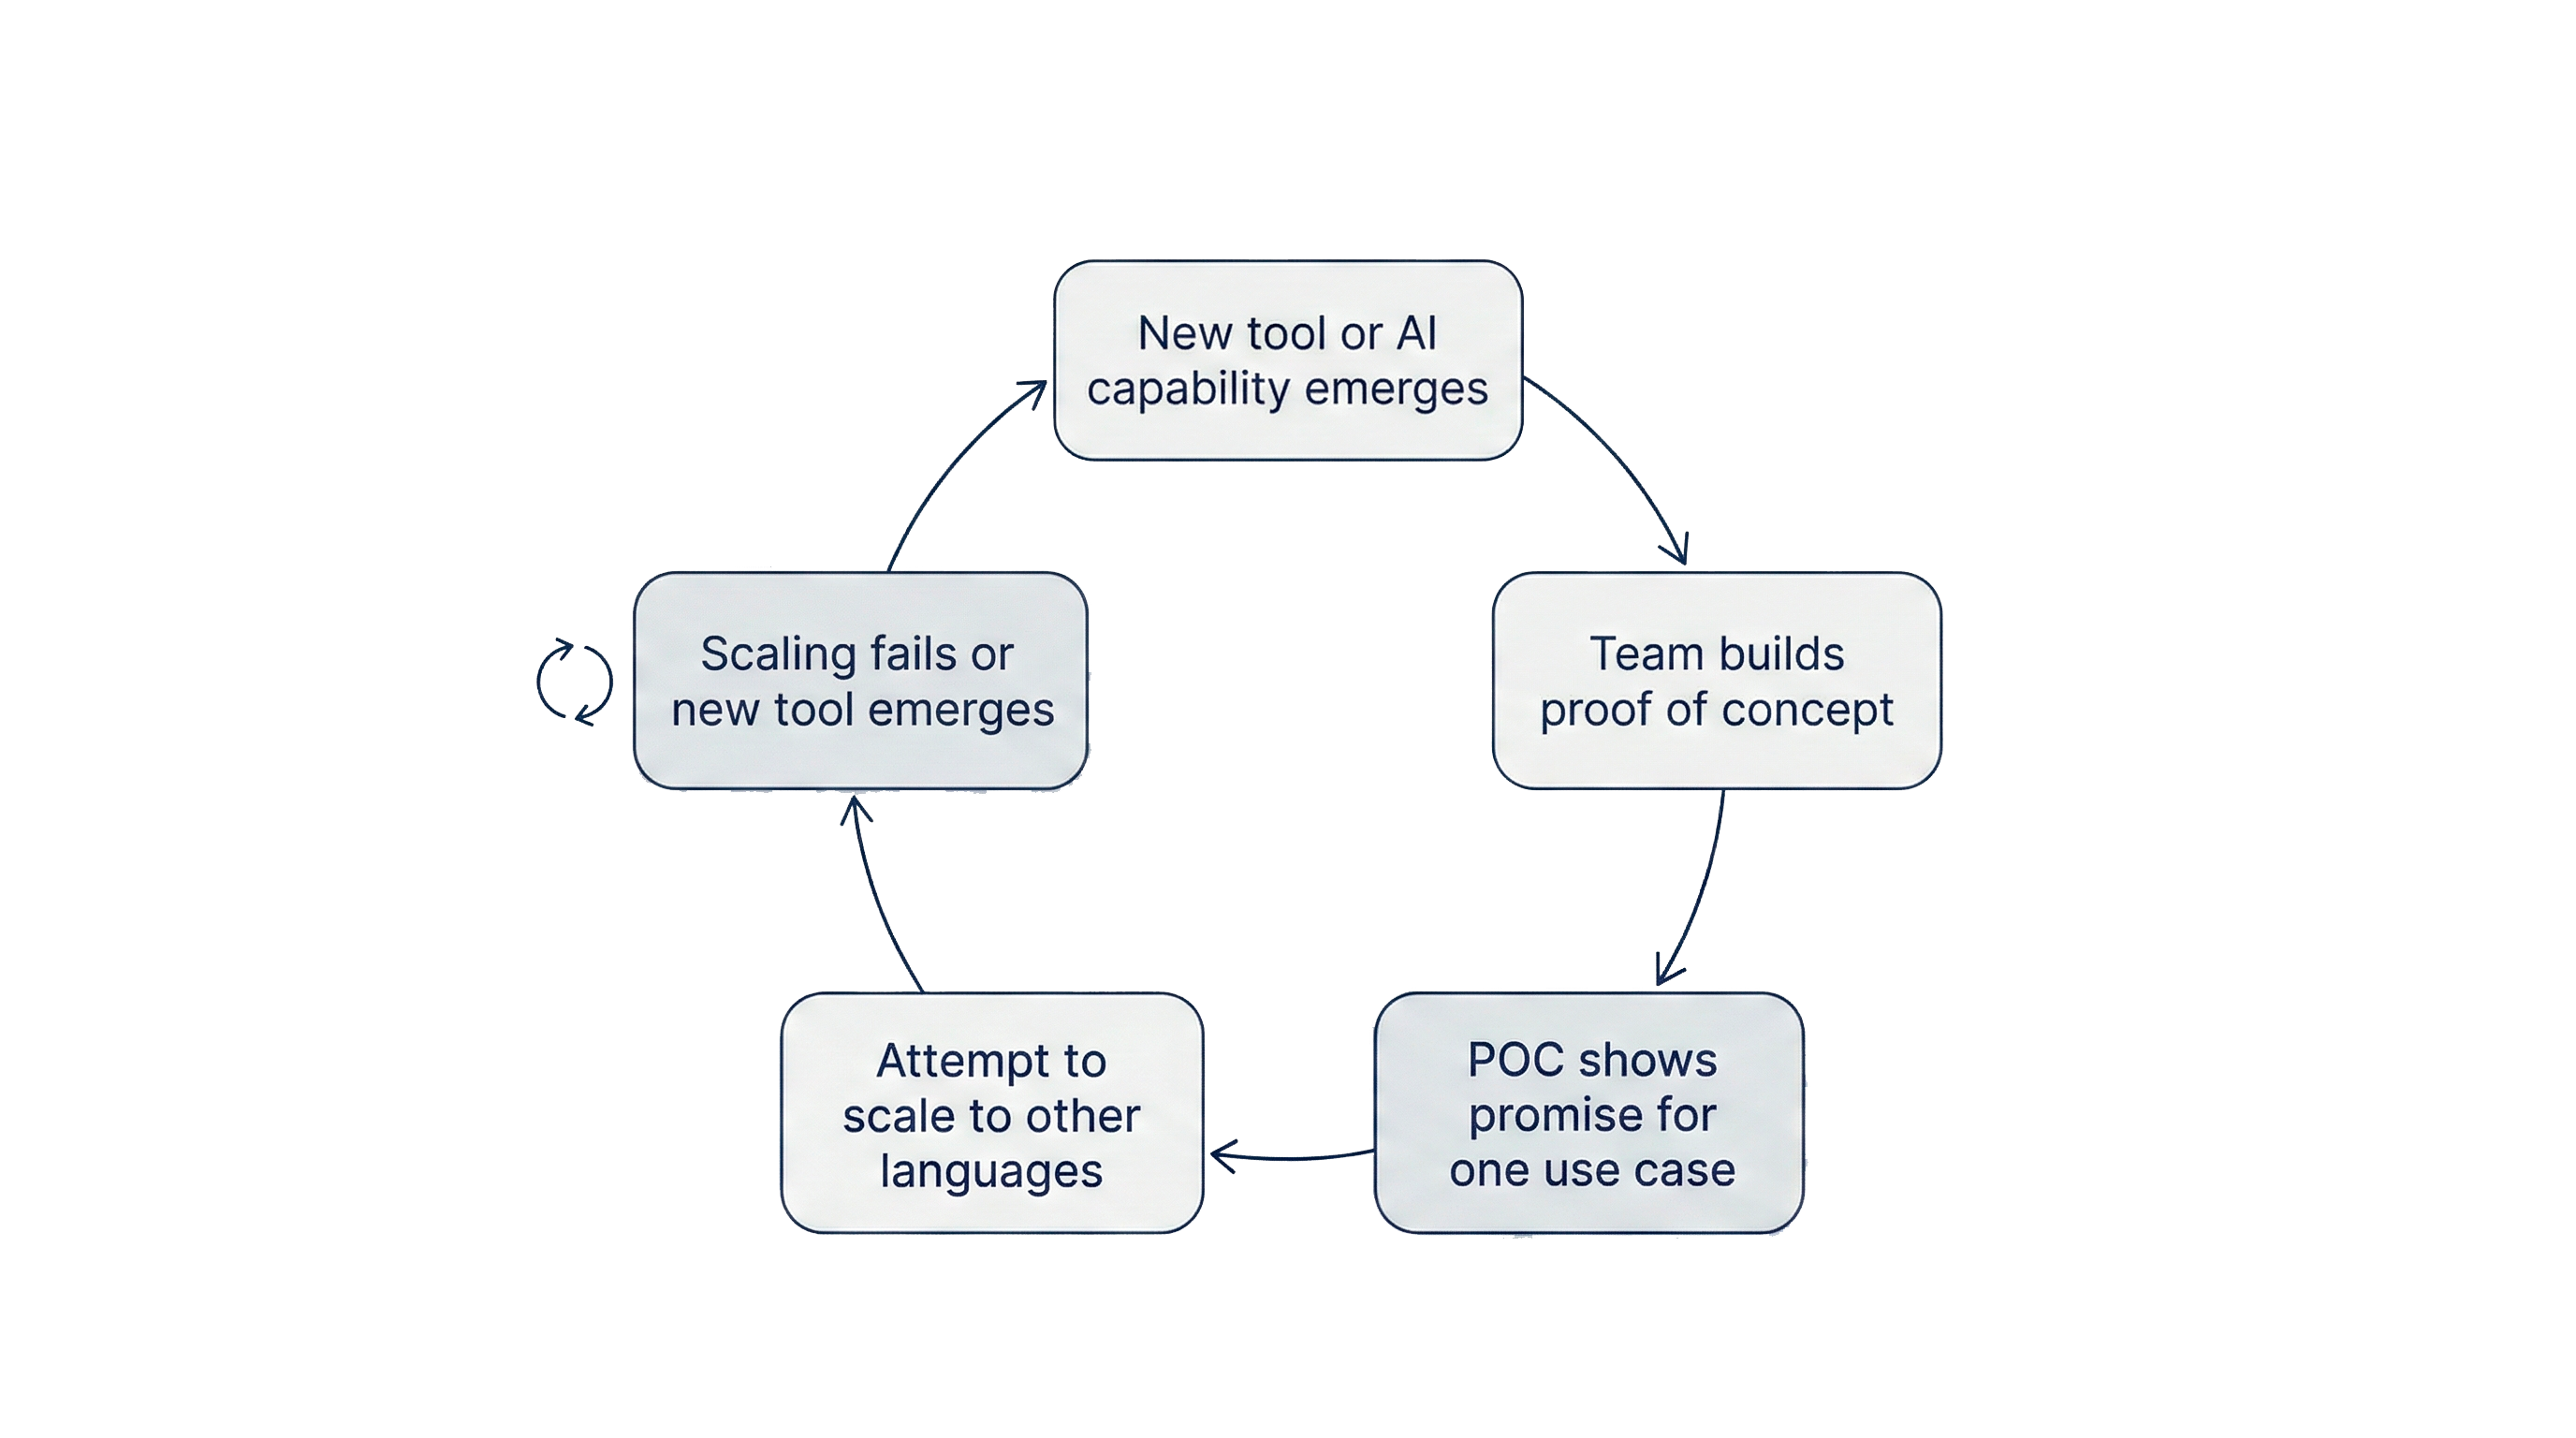
Our summary of the loop one interviewee described, and why operational stability can feel out of reach.
We asked interviewees what they value most in a language service provider. Several themes recurred.
A partner, not a supplier. Interviewees wanted a provider that acts as an extension of their team and helps solve problems, rather than one that only executes tasks. One drew the line explicitly: partners rather than vendors.
Dedicated teams and linguistic consistency. Rotating translators who sound different every time are a warning sign. One interviewee has worked with the same translator for six years.
Accountability. One interviewee named a lack of accountability as a major warning sign: a provider that deflects blame rather than taking responsibility when something goes wrong.
Flexibility with the client's tools. Leaders want providers that adapt to their tools and processes, not the other way around. One noted that small signals, such as a provider working outside the client's own tools, said a lot about it.
Delegating workflow. One interviewee would hand operational workflow management to a provider if volume grew; others named quality review and terminology as work they would hand over.
The gap between what teams track and what the business cares about came up in several conversations. Several of the leaders we spoke to found it difficult to attribute business results to localization specifically.
Some teams are experimenting with different measures: post-editing distance as a proxy for AI output quality, sentiment or retention by market, and root cause analysis of errors rather than simply counting them.
Another shift is towards risk as a quality framework. Rather than applying one quality standard to all content, some teams tier content by risk level and business importance.
| Traditional Metrics | Emerging Metrics |
|---|---|
| Word count / volume | Content risk classification |
| Cost per word | Cost per outcome (market launch, feature release) |
| Bug count (linguistic QA) | Root cause analysis of errors |
| SLA adherence (turnaround) | Time-to-market by language |
| Fuzzy match percentage | Post-editing distance |
| Vendor scorecards | LLM-assisted quality evaluation, checked against human review |
| User retention by market/language | |
| Customer support deflection by language |
The relationship between in-house teams, freelancers, and LSPs is more complex than the industry typically acknowledges.
Some of the leaders we interviewed work freelancer-first, managing direct relationships with individual translators, sometimes for years. Reasons given included cost, deeper brand knowledge and direct influence over the linguists.
But freelancer-first models have a ceiling. A manager who works with freelancers directly becomes the project manager, the QA layer, the query resolver and the context provider, on top of everything else. One solo manager agreed that, as volume grows, this makes the manager the bottleneck.
One interviewee described a shift in the content the team handles: less long-form marketing text, more product content, and blogs giving way to short-form video.
This creates a paradox. Content of the kind described as growing, such as product strings and UI copy, is often the hardest for AI to handle well, because it is short, context-poor and variable in quality. The content AI handles best, long-form and well-structured, is the kind described as shrinking.
In our view, every theme in this report points the same way: localization teams that position themselves as advisers to the business are better placed than those that remain service desks.
Some of the leaders we spoke to already describe their work in their stakeholders' terms, such as the time it takes to launch a new language or how users in each market rate the product's clarity.
There are adjacent areas where localization expertise applies directly and where, in our experience, ownership is often unclear: taxonomy, AI governance, content quality governance and multilingual SEO.
A practical checklist from Kobalt for reviewing your own localization operation. Use the unchecked items to decide where to look first. There are no right answers, only honest ones.
Our view of five shifts that will shape the localization function through 2026 and beyond.
The binary question (human or machine?) is being replaced by a spectrum. Content risk matrices, tiering content by business impact, regulatory exposure, and brand sensitivity, will become the default framework for workflow decisions.
Someone needs to own the question: "Is our AI performing equally across all our markets?" Localization teams are uniquely positioned to take this on. Expect the most forward-looking teams to expand into AI output evaluation, multilingual bias detection, and quality governance.
The one-size-fits-all LSP is fading. In its place: a mosaic of specialist partners, AI platforms, managed freelancer networks, and workflow orchestration layers. The LSPs that thrive will be the ones flexible enough to fit into any configuration.
As short-form video takes a larger share of the content companies publish, localization teams will need to handle audio and video as fluently as they handle text today.
The strain some interviewees described isn't sustainable. Companies that invest in operational stability, resisting the urge to chase every new tool and instead building repeatable processes, will retain their senior talent. Those that don't will face a talent drain at exactly the moment when experienced professionals are most valuable.
The State of Localization 2026: Insights from the Front Line was produced by Kobalt Languages, which plans and runs localization operations, whole or in defined parts, for companies working across markets.
This report draws on exploratory interviews Kobalt held between November 2025 and February 2026. Most interviewees run localization in-house at technology, e-commerce and consumer companies; a few work on the vendor or consulting side. They ranged from people running localization alone to people working in or leading larger teams. We have not named interviewees or their employers, and have left out details that could identify them.
The interviews were exploratory, semi-structured video calls of about 30 minutes. The findings are qualitative: they describe what the people we spoke to told us, and are not representative of the industry. Where we write "one", "two", "some" or "several", we mean the people we interviewed. Paraphrases are ours; we have not reproduced interviewees' words as quotations. Industry figures come from the sources linked beside each figure.
Updated to correct the description of the research and remove unsupported quantitative claims and quotations.
If any of these findings resonate, we'd like to hear your perspective. Just a conversation between people who care about this industry.
Connect on LinkedInPrefer email? ricard@kobaltlanguages.com